More topicsPeer comparison
All articles →From the deskIFRS 18
IFRS 18 for analysts
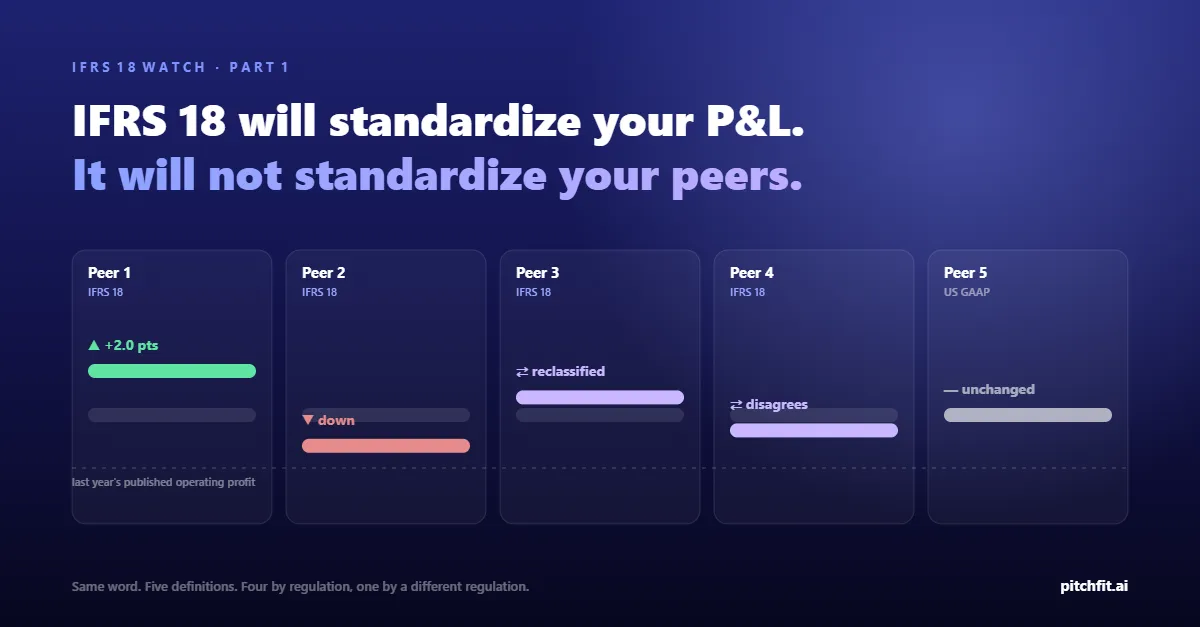
IFRS 18 Presentation and Disclosure in Financial Statements replaces IAS 1 for annual periods beginning on or after 1 January 2027, and the comparative year is restated. It defines operating profit for the first time, adds two required subtotals and brings management-defined performance measures into an audited note. These articles cover what moves in the income statement, what it does to EBIT, EBITDA and long series, and why it does not make peers comparable on its own.